 0
 0
A car accident can last only a few seconds.
The insurance claim that follows can take days or even weeks.
That is why what you do immediately after an accident matters. The photos you take, the information you collect, the way you describe what happened, and how carefully you review the insurer’s settlement can all affect how smoothly the claim moves forward.
The goal is not to argue with the other driver or try to determine the entire case at the roadside.
The goal is to protect the evidence, report the accident properly, understand your policy, and give the insurer enough information to evaluate the loss.
This guide explains how the process generally works, what information matters most, how claims adjusters evaluate vehicle damage, and what you should look at before accepting a settlement.
Important: Insurance laws, reporting requirements, deadlines, coverage and claims procedures vary by country and, in the United States, by state. The U.S.-specific examples in this article are illustrative and should not be treated as rules that apply everywhere.
1. The First Priority Is Not the Insurance Company
Immediately after a collision, it is easy to start thinking about insurance.
That should not be your first priority.
Your first priority is safety.
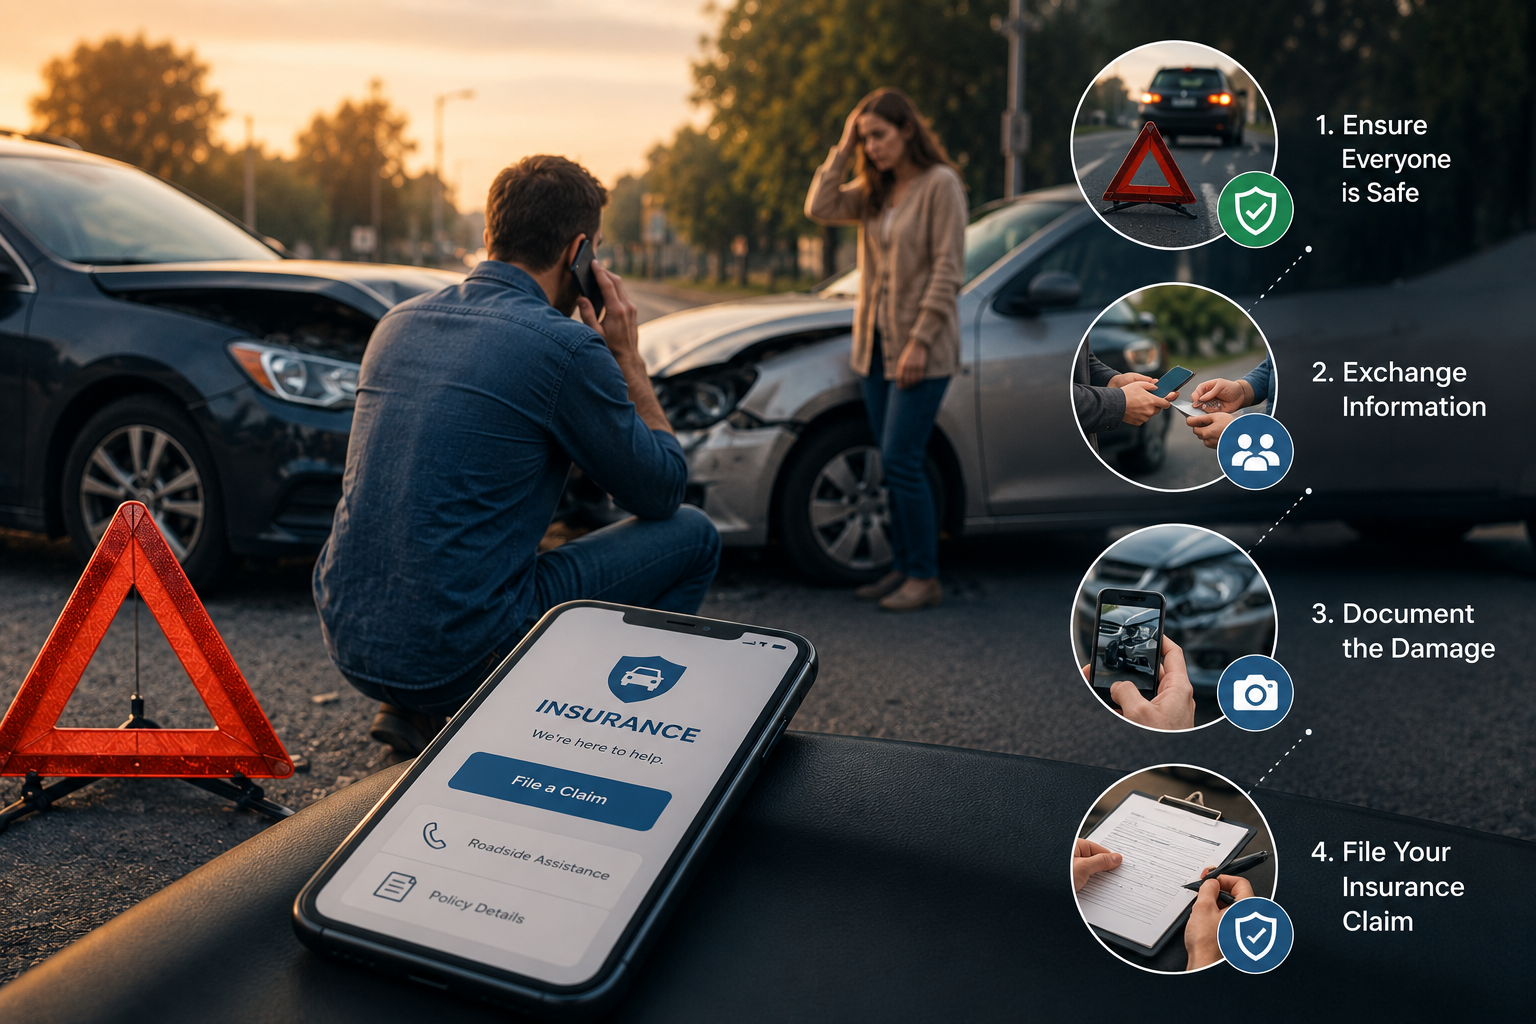
If someone is injured, emergency medical assistance should come before collecting insurance information. If the vehicles can be moved safely and doing so reduces the danger of another collision, moving them away from traffic may also be appropriate.
California’s Department of Insurance, for example, advises drivers to stop immediately, move only when it is safe, call 911 when there are injuries, notify police, and collect information from the drivers and witnesses involved.
A useful way to think about the first few minutes is:
| Priority | What to do | Why it matters |
|---|---|---|
| 1 | Check for injuries | Safety comes before property damage |
| 2 | Move to safety if appropriate | Reduces the risk of another accident |
| 3 | Contact emergency services/police when appropriate | Creates an official record where required |
| 4 | Document the scene | Preserves evidence |
| 5 | Exchange information | Allows the claim to be investigated |
| 6 | Notify your insurer | Starts the claims process |
The order matters.
Trying to collect photographs while someone is seriously injured, for example, is the wrong priority.
2. The Accident Scene Is Your First Piece of Evidence
Once everyone is safe, documentation becomes extremely important.
An insurer investigating a claim may not have been present when the accident occurred. The adjuster therefore has to reconstruct what happened using available evidence.
That evidence can include:
- photographs;
- driver and vehicle information;
- witness information;
- police reports;
- repair estimates;
- medical records;
- statements from the drivers;
- policy information; and
- other documentation relevant to the loss.
California’s consumer guidance specifically recommends obtaining driver information, license plates, vehicle identification information, witness details and photographs of vehicle damage and the accident scene.
What should you photograph?
Do not photograph only the dent.
A better record includes:
- each vehicle from several angles;
- close-up photographs of visible damage;
- license plates;
- the position of the vehicles, when safe;
- traffic signs and signals;
- road markings;
- skid marks or debris, if visible;
- nearby intersections;
- weather or road conditions when relevant; and
- damage to surrounding property.
Why wide photographs matter
Imagine a photograph showing only a damaged front bumper.
It proves that the bumper was damaged.
It may not show:
- which lane the vehicle was in;
- whether there was a stop sign;
- the road configuration;
- where the other vehicle was positioned; or
- whether visibility was limited.
A wider photograph can provide context that a close-up cannot.
3. Information You Exchange Can Become Important Later
After an accident, people sometimes focus only on getting the other driver’s phone number.
That is not enough.
When practical and safe, collect:
| Information | Example |
|---|---|
| Driver’s name | John Smith |
| Phone/contact information | Phone number |
| Driver’s license information | License details |
| License plate | ABC-123 |
| Vehicle information | Make, model, year |
| Insurance company | Insurer name |
| Policy information | Policy number if available |
| Witness information | Name and contact |
| Accident location | Street/intersection |
| Date and time | Exact or approximate time |
| Police information | Report/incident number when available |
The exact information required can vary by jurisdiction.
The important principle is simple:
Collect facts, not conclusions.
4. Be Careful About Saying “It Was My Fault”
An accident scene is usually not the right place to conduct your own liability investigation.
You may believe you caused the accident.
You may also believe the other driver clearly caused it.
But what you believe immediately after the collision may not reflect the complete evidence.
For example:
“I’m sorry. I wasn’t paying attention. This was completely my fault.”
That statement could become relevant later.
A safer approach is to describe what happened factually.
For example:
“I was traveling through the intersection when the other vehicle entered from the left.”
That describes an event without trying to make the final legal or insurance determination yourself.
This does not mean you should lie or hide facts.
It means you should distinguish between what you observed and what you conclude about liability.
California’s Department of Insurance similarly advises drivers not to sign statements concerning fault or promise to pay another party’s damages at the scene.
5. Reporting the Accident: Don’t Assume You Have Unlimited Time
One common mistake is waiting several days before notifying the insurer.
Some policies require prompt notice, while local laws and regulations can impose additional reporting requirements.
The exact deadline is not universal.
For that reason, the safest general rule is:
Notify your insurer as soon as reasonably possible and check your policy for its reporting requirements.
When you contact the insurer, have the following available:
- policy number;
- date and location of accident;
- names of the drivers;
- vehicle information;
- photographs;
- police or incident information;
- witness details; and
- a factual description of what happened.
Do not guess when answering questions.
If you do not know something, it is better to say that you do not know than to invent an answer.
6. What Happens After You File the Claim?
This is where many drivers become confused.
Filing a claim does not automatically mean the insurer agrees that the loss is covered or that it will pay the amount you request.
The insurer normally has to investigate.
A claims adjuster may:
- review the accident information;
- examine vehicle damage;
- review photographs;
- contact drivers and witnesses;
- request documentation;
- obtain repair estimates;
- investigate coverage;
- evaluate the amount of the loss; and
- communicate a settlement or coverage decision.
California’s Department of Insurance explains that an insurer may contact the claimant for detailed information and may take a written or recorded statement. It also explains that an adjuster or appraiser may inspect vehicle damage and prepare an estimate.
Think of the adjuster as an investigator—not simply a person writing a check.
The adjuster’s job is to evaluate the claim according to the policy and applicable rules.
That distinction is important.
7. How an Adjuster Looks at Vehicle Damage
Suppose your vehicle is involved in a collision and you believe the repairs will cost $8,000.
You submit the claim.
The insurer may inspect the vehicle and determine that the initial repair estimate is $6,500.
That does not necessarily mean the claim is finished.
During repairs, a body shop may discover additional damage that was not visible during the initial inspection.
For example:
| Repair item | Initial estimate | Additional damage |
|---|---|---|
| Front bumper | $1,200 | — |
| Headlight | $900 | — |
| Hood | $1,100 | — |
| Frame-related work | $2,000 | $1,500 |
| Labor/materials | $1,300 | $500 |
| Total | $6,500 | $2,000 |
The revised repair cost would be $8,500 in this hypothetical example.
The additional amount does not automatically mean the insurer must pay it. The additional damage still needs to be evaluated under the policy and claims process.
California’s consumer guidance notes that if additional damage is discovered during repairs, the repair shop may contact the insurer for approval of additional repair costs, and the insurer may reinspect the vehicle.
The practical lesson
Do not assume that the first estimate is necessarily the final repair cost.
8. Repair Shop Choice Can Depend on Your Policy and Location
Another common misunderstanding is:
“My insurance company must let me use any repair shop I want.”
That statement is too broad.
Repair-shop rules can depend on the policy and jurisdiction.
Some insurers have networks of preferred repair facilities, while some policies or local rules may allow consumers greater choice.
California’s Department of Insurance explains that an insurer may refer a consumer to a body shop, while the consumer may also choose a repair facility under the circumstances described by California rules.
So before authorizing repairs, ask:
- Who is responsible for approving the estimate?
- Can I choose my own repair shop?
- Does the insurer have a preferred network?
- What happens if additional damage is discovered?
- Who approves supplemental repairs?
- What documentation should I keep?
These questions can prevent surprises later.
9. Repair Cost Is Not Always the Same as Vehicle Value
One of the biggest issues in serious accidents is deciding whether the vehicle should be repaired or treated as a total loss.
Consider this hypothetical example:
Vehicle A
Estimated repair cost: $12,000
Estimated vehicle value before the accident: $25,000
Repairing the vehicle may be economically reasonable depending on the applicable rules and policy.
Vehicle B
Estimated repair cost: $18,000
Estimated vehicle value: $15,000
Now the economics are very different.
The insurer may evaluate whether the vehicle should be treated as a total loss under the applicable policy and jurisdiction.
In California, the Department of Insurance explains that, generally, a standard physical-damage claim may involve payment of the lesser of the amount necessary to repair the vehicle or its actual cash value, subject to policy terms and applicable requirements.
This is why simply saying:
“My car is worth $20,000.”
is not enough.
You need to understand how that value was determined.
10. Understanding Actual Cash Value
If a vehicle is declared a total loss, the discussion may shift from repair cost to vehicle value.
One important term is Actual Cash Value (ACV).
In general terms, ACV refers to the value of the vehicle immediately before the loss, subject to the policy and applicable law.
That does not necessarily mean:
- what you originally paid for the vehicle;
- what you still owe on your car loan;
- what you emotionally believe the vehicle is worth; or
- the price of the most expensive similar vehicle you find online.
For example:
| Description | Amount |
|---|---|
| Original purchase price | $28,000 |
| Remaining loan balance | $21,000 |
| Estimated pre-loss market value | $19,500 |
| Hypothetical settlement before applicable adjustments | $19,500 |
The important number for the insurance valuation may be the vehicle’s applicable pre-loss value—not your remaining loan balance.
California’s insurance regulator describes ACV in its consumer guidance and explains that, in that state, fair market value is relevant to the determination.
11. A Settlement Offer Should Be Examined, Not Automatically Accepted
Receiving a settlement offer can feel like the end of the process.
It may not be.
Before accepting an offer, review what the payment actually represents.
Ask:
- What repairs are included?
- Was the deductible applied?
- Was the vehicle considered a total loss?
- How was the vehicle’s value calculated?
- Are rental expenses covered?
- Are medical expenses part of the claim?
- Are taxes or fees included where applicable?
- Are there exclusions or limitations?
- Is there additional documentation that could change the evaluation?
The answer will depend on the type of claim, policy and jurisdiction.
Example
Suppose an insurer offers:
$14,800
You should not evaluate that number in isolation.
Instead, ask:
| Question | Why it matters |
|---|---|
| What is the repair estimate? | Determines whether the amount addresses the damage |
| What deductible applies? | Determines your out-of-pocket share |
| What vehicle value was used? | Important for total-loss claims |
| Were comparable vehicles considered? | Helps evaluate valuation |
| Are rental costs covered? | May affect your total financial loss |
| Are there policy limits? | May cap what the insurer can pay |
A settlement number without context is difficult to evaluate.
12. What If You Think the Settlement Is Too Low?
A low settlement offer does not automatically mean the insurer is acting improperly.
It means you need to understand why the insurer arrived at that number.
For example, suppose you believe your vehicle is worth $22,000 while the insurer values it at $18,500.
Instead of simply saying:
“Your offer is unfair.”
build a factual case.
You might provide:
- comparable vehicle listings;
- documentation of vehicle condition;
- maintenance records;
- receipts for relevant improvements;
- photographs;
- repair estimates; or
- other evidence relevant under the applicable valuation process.
California’s consumer guidance specifically notes that consumers can ask questions about the settlement and provides avenues for assistance when they believe a claim has been unreasonably delayed or handled.
My analysis
The strongest disagreement is usually not emotional.
It is documented.
If you want the insurer to reconsider a valuation, the useful question is not:
“Why are you trying to cheat me?”
A more productive question is:
“Can you show me how this settlement amount was calculated, including the valuation or repair information used?”
That creates something you can actually evaluate.
13. Policy Coverage Can Matter More Than the Accident Itself
Two people can experience almost identical accidents and receive different insurance outcomes.
Why?
Because their policies may be different.
Consider:
| Coverage feature | Driver A | Driver B |
|---|---|---|
| Collision coverage | Yes | No |
| Comprehensive coverage | Yes | Yes |
| Rental reimbursement | Yes | No |
| Deductible | $500 | $1,500 |
| Liability limits | Higher | Standard |
| Uninsured motorist coverage | Yes | Different/limited |
The accident may look almost identical.
The financial consequences may not be.
This is why the claim process should always be connected back to the actual policy.
California’s consumer guidance emphasizes reading the policy and reviewing coverage limits and deductibles before an accident occurs.
14. The Other Driver’s Insurance Is Not the Same as Your Own Coverage
This distinction can become important.
Suppose another driver causes an accident.
You may have a claim against that driver’s liability coverage, depending on the circumstances and local law.
But the other driver’s policy may have limits.
For example:
Your covered loss: $80,000
Other driver’s applicable liability limit: $50,000
That creates a potential $30,000 gap.
What happens next depends on the applicable law, your own insurance coverage, and the circumstances of the claim.
This is one reason consumers should understand coverages such as uninsured/underinsured motorist protection where available.
The exact rules differ significantly between jurisdictions, so this should never be treated as a universal formula.
15. Country and State Rules Matter
There is no single global car-insurance claims process.
Even within the United States, insurance regulation is not identical from state to state.
The National Association of Insurance Commissioners (NAIC) maintains state insurance-law resources, while individual state insurance departments regulate and assist consumers within their jurisdictions.
That means an article should be careful with statements such as:
“Insurance companies have exactly 15 days to respond to every claim.”
That is too broad.
A more accurate statement is:
Claim-handling deadlines and consumer protections depend on the applicable state or jurisdiction.
California example
California provides specific consumer protections and claims-handling requirements.
Its Department of Insurance states that insurers generally must acknowledge a claim, begin an investigation and provide reasonable assistance within specified time limits, and it provides additional requirements concerning claim decisions and payments.
Those California rules should not automatically be presented as rules for Texas, Florida, New York, the United Kingdom, Canada, Tanzania or another jurisdiction.
That distinction is important for accurate insurance content.
16. What Regulators Say About Claims Handling
Insurance regulators do not treat claims handling as simply a private conversation between an insurer and a customer.
The NAIC has a model regulation dealing with unfair property and casualty claims settlement practices. The model establishes standards concerning the investigation and disposition of claims, although individual states determine how their own laws and regulations operate.
State insurance departments can also investigate consumer complaints and claims-handling practices.
For example, California’s Department of Insurance operates consumer and claims-related services and can investigate complaints concerning insurance companies and claim handling.
Why this matters
If you believe a claim is being handled improperly, the answer is not necessarily to immediately threaten the insurer.
First:
- understand the policy;
- ask for the reason behind the decision;
- provide supporting documentation;
- keep written records of communications; and
- learn what complaint or appeal mechanisms are available in your jurisdiction.
17. A Simple Comparison: Good Claim Documentation vs. Weak Documentation
Imagine two drivers have similar accidents.
Driver A
- photographs the entire scene;
- photographs vehicle damage;
- records the other driver’s information;
- obtains witness contacts;
- keeps the police/incident information;
- reports promptly;
- keeps repair estimates; and
- maintains copies of communications.
Driver B
- takes one photograph;
- does not record witness information;
- forgets the exact location;
- waits several days to report;
- loses the repair estimate; and
- communicates only through memory.
Neither driver’s claim is automatically guaranteed to succeed.
But Driver A has created a much stronger documentary record.
| Claim element | Driver A | Driver B |
|---|---|---|
| Scene photographs | Extensive | Minimal |
| Vehicle damage evidence | Strong | Limited |
| Witness information | Available | Missing |
| Accident details | Recorded | Mostly memory |
| Repair documentation | Organized | Incomplete |
| Communication records | Saved | Limited |
Original analysis
Documentation does not guarantee payment.
What it does is reduce uncertainty.
And insurance claims are, in large part, exercises in reducing uncertainty.
18. Common Mistakes That Can Make a Claim Harder
Some mistakes are surprisingly simple.
Mistake 1: Waiting too long to report
A delay can create questions about when and how the damage occurred.
Mistake 2: Taking only one photograph
One picture rarely captures the entire accident scene.
Mistake 3: Guessing about facts
If you do not know the speed, distance or exact sequence, do not invent it.
Mistake 4: Repairing the vehicle before documentation
Repairs can change the physical evidence.
Mistake 5: Accepting a cash payment without understanding the consequences
A quick payment may seem convenient, but it can create problems if the damage later proves more serious.
Mistake 6: Comparing settlement numbers without comparing assumptions
A $15,000 offer and a $17,000 estimate may not be directly comparable if they use different assumptions.
Mistake 7: Ignoring the policy
Coverage, exclusions, limits and deductibles determine what the insurer is actually obligated to consider.
19. What to Keep in Your Claim File
Create one folder—digital or physical—for the entire claim.
A useful claim file might contain:
| Document | Keep it? |
|---|---|
| Insurance policy/declarations | Yes |
| Accident photographs | Yes |
| Police/incident report | Yes |
| Driver information | Yes |
| Witness information | Yes |
| Repair estimates | Yes |
| Medical documentation where relevant | Yes |
| Rental-car records | Yes |
| Emails/messages with insurer | Yes |
| Settlement offers | Yes |
| Receipts | Yes |
| Adjuster’s contact information | Yes |
This sounds basic.
But when a claim becomes complicated three weeks later, having everything in one place can save considerable time.
20. A Better Way to Evaluate Your Claim
Instead of asking only:
“How much money will I get?”
break the claim into four questions.
Question 1: Is the loss covered?
Look at the policy.
Question 2: What is the amount of the loss?
Look at repair estimates, vehicle valuation, medical documentation and other relevant evidence.
Question 3: What limits or deductibles apply?
A covered loss does not necessarily mean the insurer pays every dollar of the loss.
Question 4: Was the claim handled according to applicable rules?
This is where state or national insurance regulations can become important.
That framework is more useful than simply comparing your claim to what a friend received.
21. A Hypothetical Claim From Accident to Settlement
Consider this example.
Sarah is driving through an intersection when another vehicle hits her car.
Her immediate actions:
At the scene
- She checks whether anyone is injured.
- She calls emergency services when necessary.
- She photographs both vehicles.
- She photographs the intersection.
- She collects the other driver’s insurance information.
- She records witness information.
After leaving
She contacts her insurer and provides the accident details.
Investigation
An adjuster reviews the damage.
Initial repair estimate:
$7,200
During repairs, additional damage is discovered:
$1,800
Revised estimate:
$9,000
Sarah’s applicable deductible is:
$500
The amount payable under the hypothetical covered physical-damage claim would therefore be:
$9,000 − $500 = $8,500
This is only an illustration. Actual payment depends on the policy, coverage, applicable rules and the insurer’s evaluation.
The important lesson is that the final amount is not simply:
“The body shop said $9,000.”
There may be multiple layers between the damage and the final payment.
22. The Three Numbers You Should Not Confuse
When discussing an auto claim, people often mix up three different numbers.
Repair estimate
What someone estimates it will cost to repair the vehicle.
Vehicle value
What the vehicle was worth before the accident when a total-loss valuation is relevant.
Settlement amount
What the insurer ultimately offers or pays under the applicable policy and claim determination.
These numbers can be very different.
| Concept | Example |
|---|---|
| Repair estimate | $11,000 |
| Vehicle pre-loss value | $18,000 |
| Deductible | $1,000 |
| Hypothetical covered payment | $10,000 |
Again, these are illustrative figures, not a universal settlement formula.
23. What You Can Control—and What You Cannot
A major part of handling an insurance claim well is understanding what is actually within your control.
| Factor | Can you control it? | What you can do |
|---|---|---|
| Accident itself | No, after it happens | Focus on documentation |
| Safety response | Yes | Prioritize people and safe movement |
| Documentation | Yes | Photograph and record details |
| Reporting | Usually | Notify the insurer promptly |
| Policy coverage | Only before the accident | Understand coverage in advance |
| Deductible | Usually chosen before loss | Review policy terms |
| Repair documentation | Yes | Keep estimates and invoices |
| Insurer’s investigation | No | Cooperate and ask questions |
| Applicable law | No | Understand your jurisdiction |
| Settlement evaluation | Partly | Review evidence and calculations |
The lesson is straightforward:
Spend your energy on the variables you can actually influence.
24. My Analysis: The Best Claim Strategy Is Evidence, Not Emotion
There is a common belief that getting the best insurance settlement means being aggressive with the adjuster.
That is not necessarily the best strategy.
A stronger approach is to become organized.
If you disagree with an estimate, identify the exact difference.
If you disagree with a vehicle valuation, ask how the value was calculated.
If additional damage is discovered, document it.
If you believe an expense should be covered, point to the relevant policy provision and provide the supporting documentation.
In other words:
Replace “I think this is unfair” with “Here is the evidence that supports my position.”
That does not guarantee a different result.
But it creates a much stronger basis for discussion.
25. A Practical Claim Checklist
Before considering your claim complete, ask yourself:
At the accident scene
- Is everyone safe?
- Did I contact emergency services when necessary?
- Did I document the scene?
- Did I photograph all visible damage?
- Did I collect the other driver’s information?
- Did I collect witness information where available?
When reporting
- Did I notify my insurer?
- Did I provide factual information?
- Did I obtain a claim number?
- Do I know who the adjuster is?
- Do I know what documents the insurer needs?
During the investigation
- Did I keep copies of estimates?
- Did I document additional damage?
- Did I keep communication records?
- Do I understand my deductible?
- Do I understand which coverage applies?
Before settlement
- Do I understand how the amount was calculated?
- Did I review the repair estimate or vehicle valuation?
- Did I check applicable policy limits?
- Did I consider covered rental or other relevant expenses?
- Do I understand what accepting the settlement means?
26. The Bottom Line
Filing an auto insurance claim is not simply a matter of calling the insurer and waiting for a check.
A well-managed claim starts with what happens at the accident scene.
Protect people first. Document the facts. Report the accident promptly. Understand your policy. Cooperate with the investigation. Review the repair estimate or vehicle valuation carefully. And do not evaluate a settlement number without understanding how it was calculated.
The most important thing to remember is that insurance claims are built around evidence.
Your photographs, reports, estimates, policy documents and other records help establish what happened and what the loss may be worth.
And if something does not make sense, ask the insurer to explain the calculation rather than simply accepting or rejecting the number.
For U.S. consumers, the exact rules can vary by state, and state insurance departments are an important source of consumer guidance and complaint assistance. The NAIC also provides consumer and state-law resources for understanding auto insurance.
The goal is not to make the loudest argument after an accident.
The goal is to build the clearest record of what happened, what was damaged, what your policy covers, and why the proposed settlement is—or is not—reasonable.


Average Rating